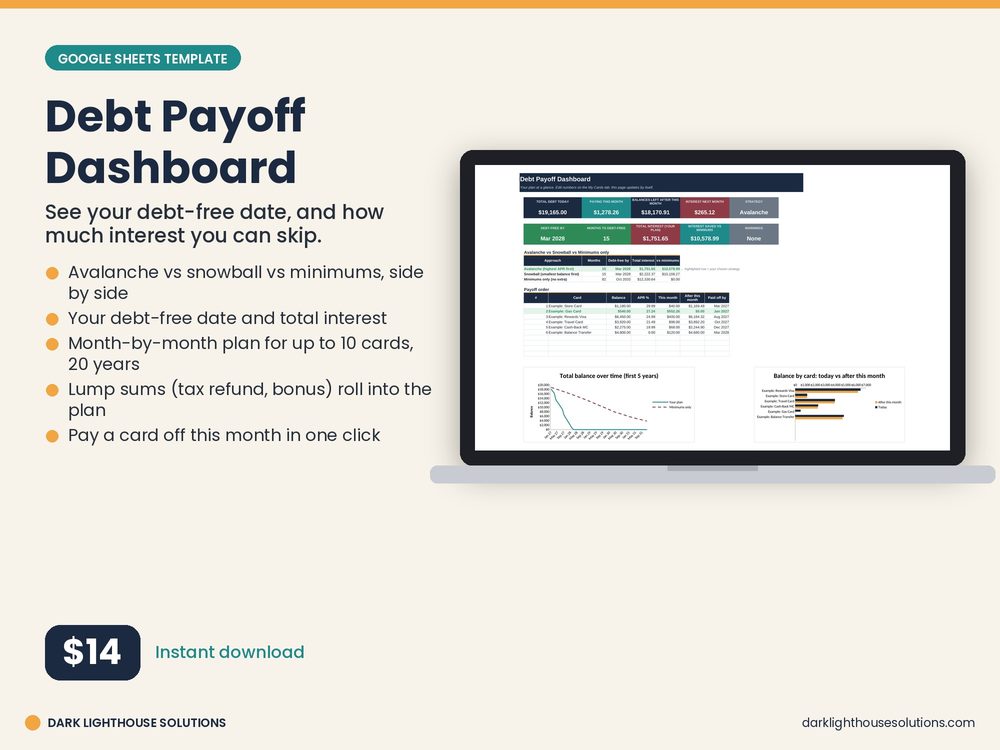
Debt Payoff Dashboard
Type in your cards. Get your payoff order, monthly plan, debt-free date and interest saved, automatically.
$14Buy now
Free tools › Debt payoff calculator
Enter your debts and an extra monthly payment. See your debt-free date, total interest and payoff order for both methods, side by side. Free, no sign-up, and nothing leaves your browser.
The Debt Payoff Dashboard does this math in Google Sheets and updates as your balances drop. The bundle adds Budget by Paycheck, Sinking Funds and two more.
Type in your cards. Get your payoff order, monthly plan, debt-free date and interest saved, automatically.
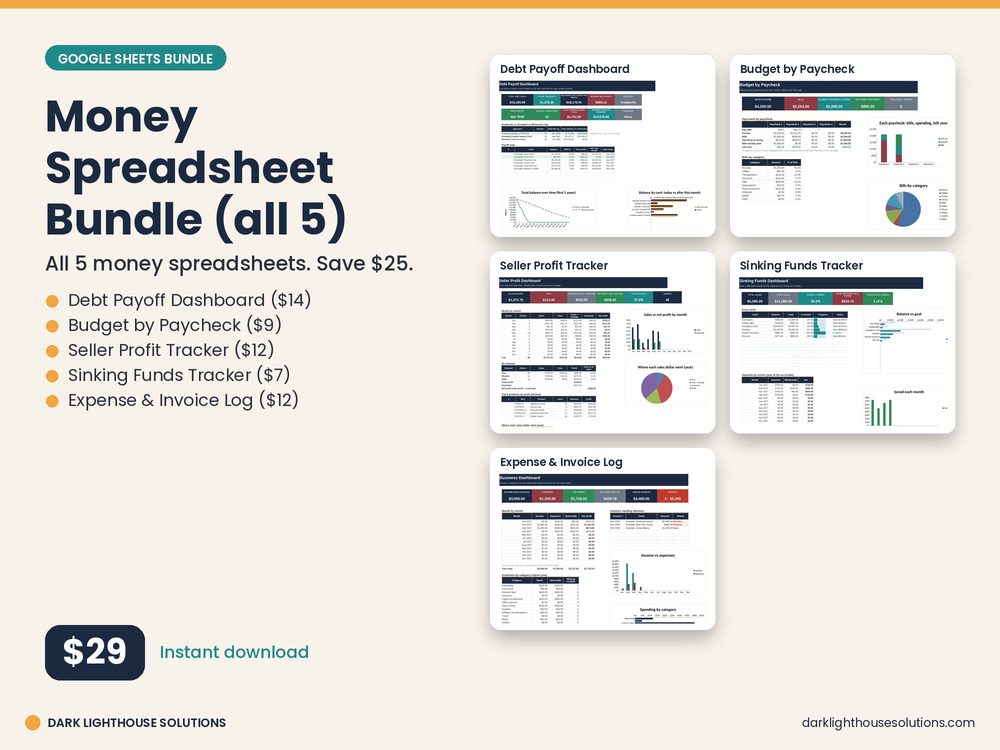
Debt Payoff Dashboard, Budget by Paycheck, Sinking Funds, Seller Profit Tracker and Expense & Invoice Log. $54 bought separately.
Both methods start the same way: list every debt, keep paying every minimum, and find one fixed extra amount you can add each month. The only difference is which debt gets the extra money first.
In both, when a debt is paid off you don't get to keep its minimum payment. It rolls into the next debt on the list. That roll-over is why the payoff speeds up near the end: by the last debt, you're throwing every freed-up minimum at it.
The month-by-month table shows what you'd pay, how much of it is interest and how much you'd still owe after each month, plus the month each debt is gone.
The biggest lever is the extra payment, not the method. Try raising it by $25 or $50 and watch how many months drop off. If one card has a much higher APR than the rest, asking for a lower rate or using a 0% balance transfer (watch the transfer fee) can beat either method. Once you have a plan, write the debt-free month somewhere you'll see it, and check your balances once a month so the plan matches reality.
A calculator gives you the plan once. If you want it to stay up to date as you pay (balances, interest saved, progress bars and next month's payments), the template below does that in Google Sheets.
Avalanche (highest interest rate first) always costs the same or less in interest, so it's the better deal on paper. Snowball (smallest balance first) clears a whole debt sooner, and that early win keeps a lot of people going. If the interest difference this calculator shows is small, pick the one you'll stick with.
It's anything you can pay on top of all your minimum payments combined. The calculator sends it to one focus debt at a time. When a debt is paid off, its minimum rolls into the next one too, so your total monthly payment stays the same until everything is gone.
If a minimum payment is smaller than the interest that debt charges each month, the balance grows instead of shrinking. Raise the minimum or the extra payment until the calculator shows a payoff date.
It compounds interest monthly at APR ÷ 12 and assumes your rates, minimums and extra payment stay the same and you add no new charges. Real statements calculate daily interest and minimums that shrink, so treat the dates as a close estimate, not a quote.